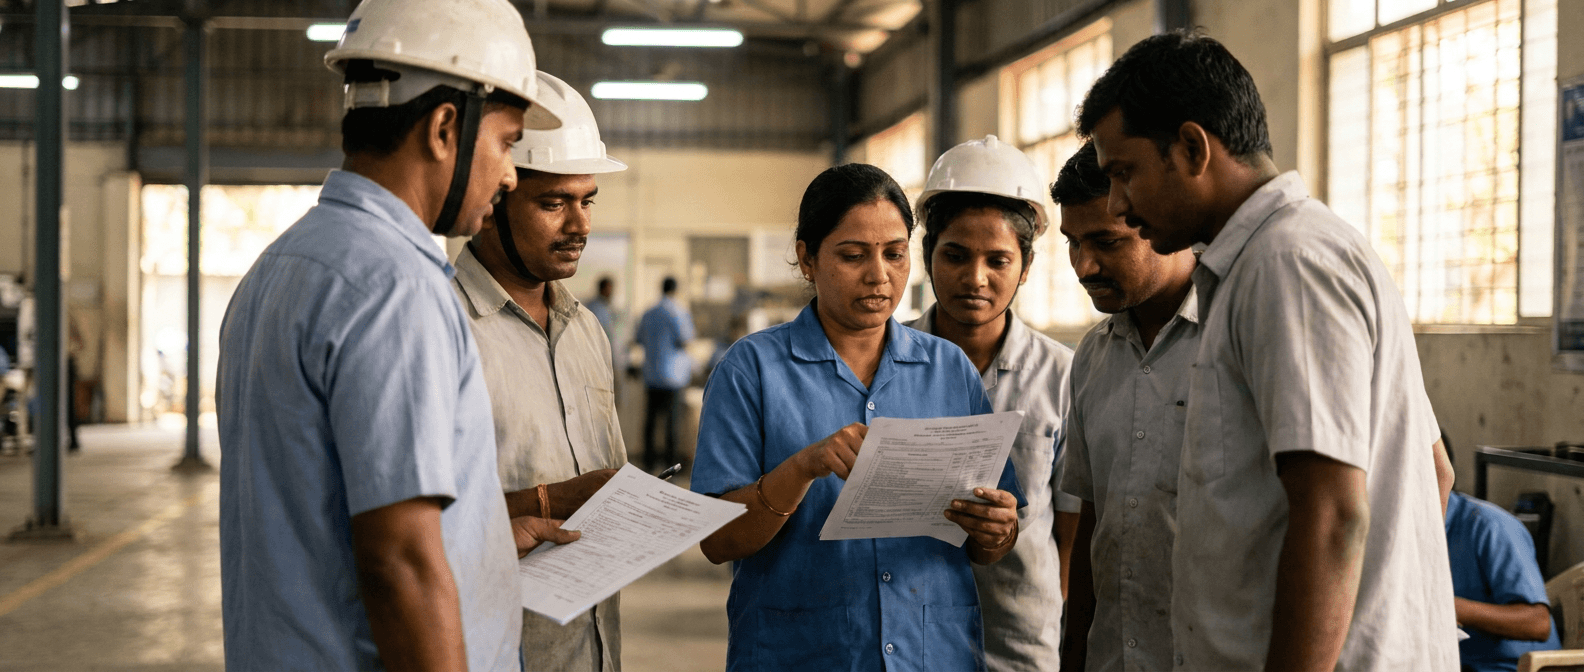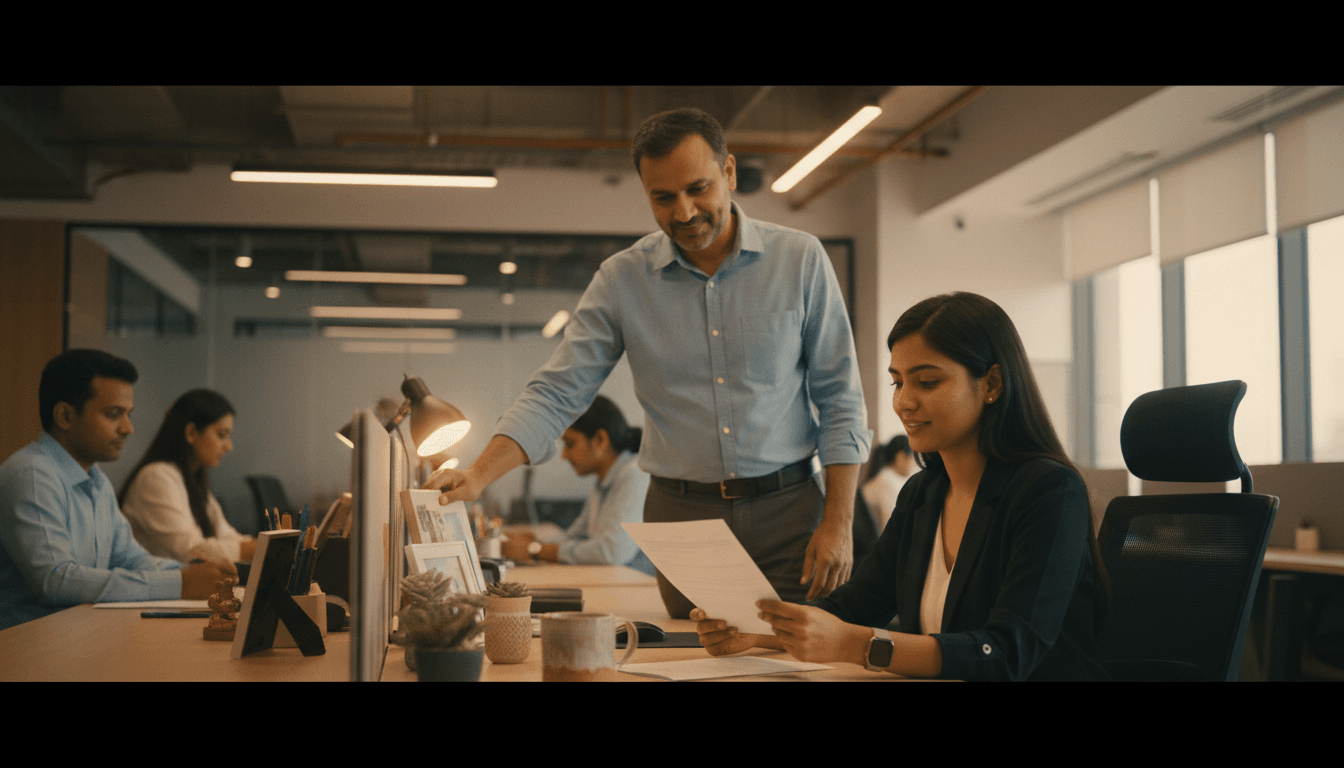
Group health insurance improves employee retention and morale by reducing an employee's financial anxiety during medical events and by making the employer's support visible in a practical, high-value way. It helps most when the cover is easy to use, clearly explained, and includes benefits employees actually need, such as cashless hospitalisation, dependent cover, maternity cover, or coverage for parents where the employer chooses to include them.
For an employer, group health insurance is not only a medical benefit. It is part of the employee value proposition, which is the total package of salary, benefits, culture, growth, and security that influences whether people join, stay, and feel supported at work.
How Does A Group Health Insurance Impact Employee Retention?
A group health insurance policy or corporate health policy can improve retention of employees because it gives them a benefit that they may not want to lose when they leave the company. If the health policy covers employees dependents or has useful features such as cashless and reimbursement claims, an employee will compare not only salary but also the value of losing that coverage when considering another job.
The retention effect usually comes from four practical levers:
| Retention lever | What the employee experiences | How it can affect leaving decisions |
|---|---|---|
| Financial protection | The employee does not have to rely only on savings during a hospitalisation. | A job that protects the household becomes harder to replace with a similar salary-only offer. |
| Dependent security | The employee may be able to cover spouse, children, or parents if the employer has included them. | Employees with family responsibilities may place a higher value on staying with the employer. |
| Immediate workplace support | HR or the insurer can guide the employee during admission, claims, or documentation. | Employees remember support during a difficult event, which can increase loyalty. |
| Perceived fairness | A standard benefit is available to eligible employees across the organisation. | A visible benefit can reduce the feeling that only senior employees receive meaningful protection. |
The effect of the retention depends on the policy structure prepared by an employer. A low sum insured, means low coverages in a cover which includes small number of network hospitals, many exclusions and a claim process which is difficult to understand this will have very less effect on employees than a policy that employees can use easily and have higher coverage with high sum insured and an easy process of claim
How Does Group Health Insurance Improve Employee Morale?
A group health insurance can improve employees morale because it replaces an employer's support into something stronger. Health insurance answers larger concerns: If an employee needs medical help or any of their family members then group policy helps them during these kinds of emergencies.A salary increment is useful, but health insurance answers a larger concern: what happens if the employee or a family member needs hospital care.
The belief system of an employee is strongest when they understand exactly what is covered under the policy and whom to contact when they are facing problems in claims. If a benefit is hidden in a policy document and is announced during onboarding this does not create a good impression among employees. If claims, renewal reminders, HR communication was done perfectly then the same confidence should be maintained throughout the policy.
- Reduction in unpredictability : employees know there is a secure medical cover available during hospitalisation.
- It builds trust: Employees see the employer as a support system beyond just day-to-today work output.
- It supports attendance and focus: If the claim process is clear to employees who are going through some medical problem they spend less time in understanding the cover.
- It helps during personal crises: quick HR and insurer support during admission or discharge can affect how an employee feels about the workplace.
Group Health Insurance - Features That Ensure Higher Employee Retention
The benefits that matter most are the ones employees can use and can explain to their families. A group policy with a higher premium but less coverage and bad communication with insurance companies, TPA or brokers may feel less valuable than a simpler policy that employees understand and can use when needed.
| Policy feature | Retention and morale impact | What employers should make clear |
|---|---|---|
| Sum insured | A higher available cover can give employees more confidence during hospitalisation. | The exact cover amount per employee or per family, and whether it is shared among dependents. |
| Dependent cover | Cover for spouse, children, or parents can make the benefit more relevant to household needs. | Which dependents are eligible, age limits, and whether employees must pay extra for any dependents. |
| Cashless network | Cashless admission can reduce stress at the time of hospitalisation. | The hospital search process, pre-authorisation steps, and emergency contact route. |
| Pre-existing disease terms | Employees with ongoing conditions may value a policy more if the terms are favourable. | Whether pre-existing diseases are covered from day one or after a waiting period, as per the policy. |
| Maternity benefits | Maternity cover can strongly affect morale for eligible employees planning a family. | Eligibility, waiting period if any, limits, newborn cover, and claim documents. |
| Room rent and co-pay | Restrictions can affect the employee's out-of-pocket cost at discharge. | Room rent limits, co-pay percentage if any, and examples of how deductions apply. |
| Claim support | Fast help can turn the policy into a remembered employee-support moment. | HR contact, insurer helpline, escalation path, and expected document list. |
Usability matters more than the announcement
A group health insurance policy supports retention only when employees can actually use it. If the sum insured is too low, the hospital network is inconvenient, or employees do not know the claim process, the policy may exist on paper but have limited effect on morale.
Map employee needs first
Identify whether employees need individual-only cover, family cover, parental cover, maternity benefits, or optional top-ups. The useful policy is the one that matches the workforce, not the one with the longest feature list.
Choose the policy design clearly
Decide the sum insured, eligible dependents, co-pay, room rent limit, maternity terms, pre-existing disease terms, and hospital network before announcing the benefit.
Communicate the benefit in plain language
Tell employees the exact cover amount, who is covered, what is excluded, how cashless admission works, and whom to contact during an emergency.
Make claims support visible
Give HR, managers, and employees an easy to understand claim rule book with how they can raise claims, search for network hospitals, pre-authorisation steps, document requirements, and claim support or help desk contact.
Review the policy every renewal
Review claim issues, employee feedback, utilisation, and renewal changes every year so the policy remains relevant as the workforce changes.
How Can Employers Measure The Impact of Group Health Insurance?
The effect should be measured through both retention data and employee feedback. Retention data shows whether people are staying, while feedback shows whether employees value the benefit.
| Metric | What it tells you | How to read it |
|---|---|---|
| Voluntary attrition rate | Whether employees are leaving by choice. | Compare the rate before and after benefit changes, while also checking salary, workload, and manager changes. |
| Offer acceptance feedback | Whether candidates consider the benefit meaningful. | Ask new joiners which benefits affected their decision to accept the offer. |
| Employee engagement survey | Whether employees feel supported by the organisation. | Include a specific question on health benefits instead of asking only a broad satisfaction question. |
| Claims experience feedback | Whether the policy works during real use. | Track delays, confusion, claim rejections, hospital issues, and HR support quality. |
| Renewal participation or top-up interest | Whether employees see value in continuing or expanding cover. | High interest can indicate that employees understand and value the cover. |
Key Takeaways
Group health insurance improves retention by making the overall experience of an employee valuable and harder to replace by just comparing salaries.
When an employee understands the importance of a health plan it improves their morale. They realise that they can use the hospital network, easy claim support, family cover etc.
Competitive salaries, good managers, healthy workplace, career growth etc cannot replace a good coverage group health insurance.
Employee retention impact should be considered through employee feedback and their experience with policy. A cost review can only compare the annual or monthly premium.
Frequently Asked Questions
Yes, a group health insurance helps a small business to retain their employees because it adds a valuable and useful experience in the employment package. Group policy effect is stronger when it really comes in use of the employees and the claims processes are seamless and easy to understand.
The value of a group health policy depends on the employee. Employees in the young age bracket may value an individual cover and cashless claims whereas employees with families values a family group policy, employees in their mid-career have higher values because of parents inclusion in cover or higher sum insured for them. A company purchasing a policy should always consider employee needs before finalising the policy cover.
No, it is not usually enough to stop an employee from leaving an organisation. Employees can still leave for a higher pay, better managers, career growth, flexible working culture and lower stress. Group health insurance works best as a part of a broader employee retention plan.
HR's or employers should explain to employees about the policy cover in detail like sum insured they are getting, eligibility of their family members, claims category, exclusions in policy, network hospitals, claims or HR contact details. These information are necessary for an employee; they should not have discovered these details during an emergency.
A company can know if their employees are improving in terms of morale or not by tracking their feedback regularly, survey responses, claim experiences and feedback during renewal. These are few measures that an employer can maintain because they affect retention of an employee.
Yes, optional top-ups improve the value of group policy which makes it even more useful for the employees. Employees can increase their benefits apart from what they are getting from a group policy. This depends on the top-up cost, eligibility, waiting periods, and whether dependents are included or not.
About the authors
Nikita Joshi
Written by · Marketing Specialist - ACKO for BusinessNikita Joshi works on Group Mediclaim at Acko General Insurance, spanning client advisory, growth analytics, and marketing for the SME segment. She combines data-driven insight with content and campaign strategy to build credible, useful health insurance experiences for employers and employees alike.
Nitesh Kapur
Reviewed by · Senior Director – Underwriting & Claims, Group Health Insurance at ACKOWith over 15 years of experience in health insurance underwriting, he has led group health insurance strategy, risk assessment, and policy design. He has held leadership roles at leading insurers, building risk frameworks, evaluating complex health risks, and strengthening underwriting standards.