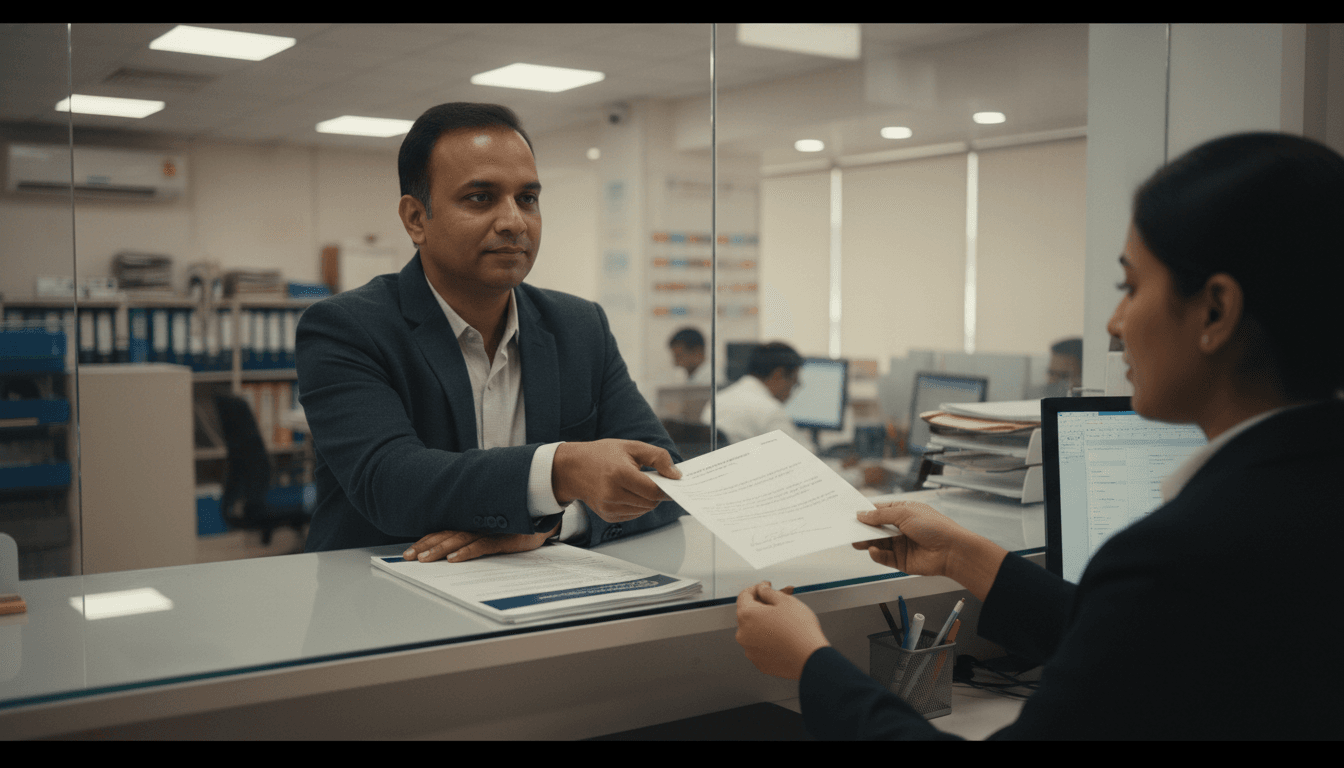
An employer can cancel a group health insurance policy by following the insurer's cancellation process and complying with the terms and conditions of the policy. Employers may choose to cancel a group health insurance policy due to cost considerations, business restructuring, workforce changes, or when switching to another insurer.
In this article, you'll learn how to cancel a group health insurance policy, the different cancellation scenarios, the refund rules that may apply, and the factors employers should consider before terminating coverage for employees.
Who can cancel a group health policy?
Any group health master policy can only be cancelled by the policyholder whose name is on the master policy. This is the company that signs the policy document with the insurer and pays the premium for the policy. This does not include any employees or members who are part of the insurance policy.
Here is how the roles differ:
| Party | Role | Can they cancel the policy? |
|---|---|---|
| Policyholder (employer/association/bank) | Buys the master policy and pays premium | Yes, the whole policy |
| Group administrator / HR | Manages the member list | Can add or remove members, not cancel the master policy unless authorised |
| Individual member/employee | Covered under the policy | No, can only opt out or be removed |
| Dependents of a member | Covered through the member | No |
An employee who wants to stop being covered, should ask the HR to remove them from the group list, not to cancel the policy. If the employer or group organiser want to cancel the plan, they can directly cancel the master policy.
Documents Required to Cancel a Group Health Insurance Policy
The documents required to cancel a corporate health insurance policy may vary depending on the insurer and the policy terms. Employers may be asked to provide the following:
- Cancellation Request Letter: The employer can send a cancellation request mentioning they want to cancel the policy and the preferred cancellation date.
- Policy Details: Any policy details including the policy number, policy schedule, or other policy-related information may be shared with the insurance company.
- Authorisation Documents: These are generally asked for to verify if the cancellation request has been made by an authorised person in the policyholder company.
- Cancellation Forms: Forms specified by the insurance company needed to process the cancellation request.
- Bank Account Details: The account details are usually required if the insurance company needs to issue any refund to company for any unused premium.
Things to Consider Before Cancelling a Group Health Policy
- Employee Coverage: Since the employees health coverage will end with the policy termination, employers should consider arranging alternative options to minimise gaps in employee health insurance protection after the policy ends.
- Refund Eligibility: The refund amount depends on the unused policy related benefits, the terms and conditions, overall claims during the financial year, and the remaining policy period.
Review the Policy Documents
Check the policy agreement for cancellation terms, notice requirements, refund provisions, and any applicable conditions.
Assess Employee Coverage Needs
Consider arranging alternative health insurance coverage to help avoid gaps in employee protection after the policy ends.
Notify the Insurer
Submit a written cancellation request to the insurer or through the authorised intermediary, if applicable.
Provide Required Information
Share the policy details, company information, desired cancellation date, and any other information requested by the insurer.
Submit Supporting Documents
Provide any forms or documents required to process the cancellation request.
Obtain Confirmation
Request written confirmation from the insurer showing the effective cancellation date and details of any applicable refund.
Common Group Health Insurance Policy Termination Scenarios
Here are three common group health insurance policy termination scenarios:
Scenario 1:
Cancellation by the Employer: An employer may choose to cancel a group health insurance policy before its expiry due to business restructuring, changes in employee benefits, cost considerations, or a switch to another insurer.
Depending on the policy terms, claims history, and the remaining policy period, the insurer may refund a portion of the unused premium after applicable deductions.
Scenario 2:
Non-Renewal of the Policy: A group health insurance policy may also end when the employer decides not to renew it at the end of the policy term. Unlike mid-term cancellation, non-renewal takes effect only upon policy expiry.
Employers may choose not to renew a policy if they are moving to another insurer, revising employee benefits, or reassessing business requirements. In such cases, employees should be informed in advance so they can make alternative healthcare coverage arrangements if necessary.
Scenario 3:
Cancellation by the Insurer: In certain circumstances, an insurer may cancel or terminate a group health insurance policy in accordance with the terms and conditions of the contract. This may happen in cases involving fraud, material misrepresentation, non-disclosure of important information, or violations of policy conditions.
If an insurer decides to terminate the policy, it must follow the cancellation provisions outlined in the policy document. Any applicable refund, if allowed, will be governed by the policy terms and the circumstances leading to the cancellation.
Learn the common reasons and practical tips to avoid claim rejection in our detailed guide.
Are there Charges or Catches to Watch Out for in Case of Group Health Termination?
Beyond the refund method, a few conditions can reduce what you get back or delay the cancellation:
- Minimum term or lock-in: some group contracts require the policy to run for a set period; check the schedule before cancelling.
- Notice period: insurers often need advance written notice, so the effective cancellation date may be later than your request date.
- Claims made: a paid or pending claim can wipe out the refund entirely.
- Pending premium: any unpaid instalments are adjusted against the refund.
- Documentation gaps: a missing authorisation or KYC document delays processing.
Confirm the exact figures and conditions with your insurer in writing before you finalise the cancellation date.
Cancelling ends cover for everyone at once
When the master policy is cancelled, every member and dependent under it loses cover from the cancellation date. Any hospitalisation after that date is not payable, even if the illness began while the policy was active. Plan the timing so members are not left without health cover.
Are there charges or catches to watch for?
Beyond the refund method, a few conditions can reduce what you get back or delay the cancellation:
- Minimum term or lock-in: some group contracts require the policy to run for a set period; check the schedule before cancelling.
- Notice period: insurers often need advance written notice, so the effective cancellation date may be later than your request date.
- Claims made: a paid or pending claim can wipe out the refund entirely.
- Pending premium: any unpaid instalments are adjusted against the refund.
- Documentation gaps: a missing authorisation or KYC document delays processing.
Confirm the exact figures and conditions with your insurer in writing before you finalise the cancellation date.
Employee Coverage After Policy Cancellation
A group health insurance policy covers your staff only as long as it's active and they're on the payroll. When you cancel it, or when someone leaves the job, that protection doesn't carry over. Coverage is considered void from the effective date of cancellation in most cases.
- Hospitalisation costs: Room rent, ICU charges, surgeon fees, and medicines during an inpatient stay are no longer reimbursed after the cancellation date.
- Pre-existing diseases: The day-one waiver your employees enjoyed under the group plan goes away, and any new individual policy they buy will usually restart the standard waiting period.
- Maternity benefits: Any delivery cover, along with its sub-limits, ends with the policy.
- Family members: Cover extended to an employee's spouse, children, and dependent parents stops at the same time theirs does.
Because you set the sum insured as the employer, your employees can't keep it once the plan is cancelled. Any claim for treatment that begins after the cancellation date won't be honoured. This is exactly why timing matters, and why it helps to give your team enough notice so they can buy personal cover before the group plan lapses, leaving no gap in protection.
Conclusion
Before cancelling a group health insurance policy, it is important to understand the applicable notice requirements, refund provisions, and the impact on employee coverage. Employers should also plan for alternative coverage, if required, to avoid gaps in health insurance protection for employees.
Frequently asked questions
Yes, employers can usually cancel a group health insurance policy before it expires. However, they must follow the insurer's cancellation process and the terms mentioned in the policy document.
The refund amount, if any, depends on factors such as the insurer's terms and conditions, claims history, and the remaining policy period. Some insurers may refund a portion of the unused premium after applicable deductions, while others may have different refund rules.
Employee coverage generally ends on the policy's effective cancellation date. To avoid gaps in health insurance protection, employers may consider arranging alternative coverage before the existing policy ends.
Yes, a company can switch from one group health insurance provider to another. Before making the switch, employers should compare coverage, benefits, waiting periods, and policy start dates.
Claims arising during the active policy period are generally processed according to the policy terms and conditions, even if the policy is cancelled later. However, claim settlement remains subject to the insurer's review and the coverage terms of the policy.
About the authors

Neviya Laishram
Written by · Senior Editor – Health, Life and Group Health Insurance Content at ACKOWith a journalism background, she brings 9 years of experience in strategising and editing health, life, and group health insurance content. Having written for magazines and digital publications, she combines research and editorial expertise to create credible, useful content for readers.
Nitesh Kapur
Reviewed by · Senior Director – Underwriting & Claims, Group Health Insurance at ACKOWith over 15 years of experience in health insurance underwriting, he has led group health insurance strategy, risk assessment, and policy design. He has held leadership roles at leading insurers, building risk frameworks, evaluating complex health risks, and strengthening underwriting standards.





